India's solar module component market seen doubling to $7.8 billion by FY28
A new report projects sharp growth in the domestic supply chain for solar module parts, though the sector still leans heavily on imports.
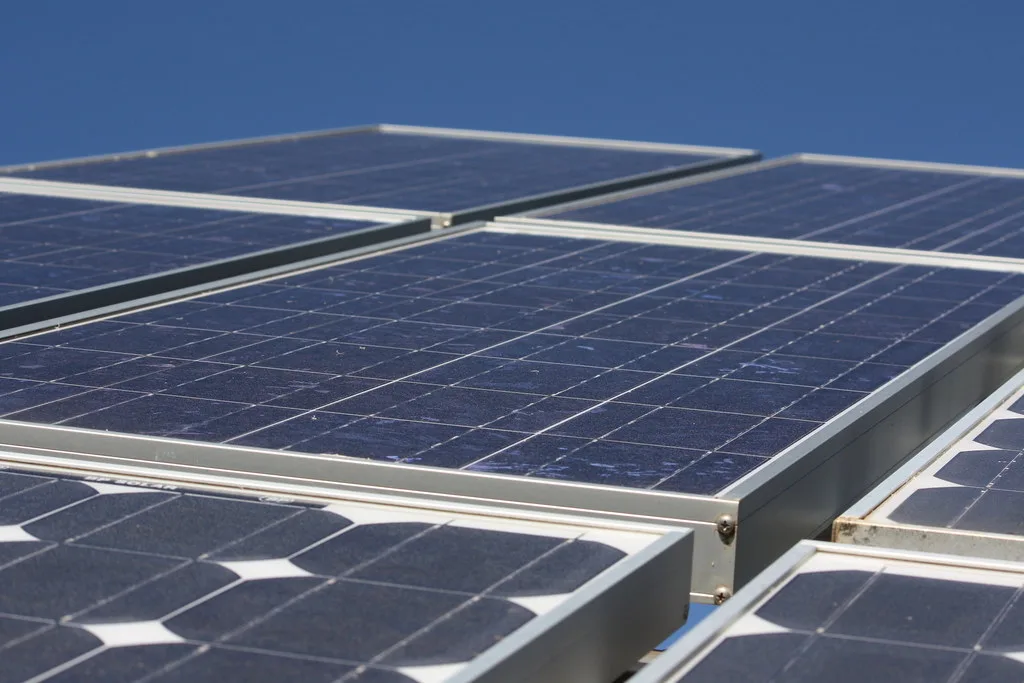
India's market for solar module components could more than double to $7.8 billion by FY28, according to a report cited by The Economic Times. The projection points to rapid expansion in the upstream end of the country's solar manufacturing chain, the part that supplies cells, glass, frames, junction boxes and backsheets to module assemblers.
The figure marks a steep climb from current levels. Doubling in a few years is a big ask for any supply chain. For solar components, it rides on two things: India's push to build modules at home, and the basic arithmetic of a market that has been growing fast off a small base.
Why the component end matters
Most of the public attention on India's solar story goes to module assembly. That's the visible, jobs-heavy end. But modules are only as domestic as the parts that go into them. Cells, glass and frames often come from China and Southeast Asia, and that dependence is what the component market projection speaks to.
A $7.8 billion component market by FY28 would mean more of that spend landing inside India. It would also mean more capacity for the smaller suppliers who feed the big module lines. Those suppliers have struggled to scale, partly because module makers can import parts cheaper than they can buy them locally.
The report doesn't spell out how much of the projected market would be met by domestic production and how much by imports. That gap is the number that matters most for the government's self-reliance goals.
The policy backdrop
New Delhi has spent the last few years trying to pull the solar supply chain inward. The production-linked incentive scheme for high-efficiency modules, the basic customs duty on imported cells and modules, and the approved list of models and manufacturers have all pushed in that direction. Module capacity has grown quickly. Component capacity has lagged.
That lag is the opening the report is betting on. If module lines keep expanding, the demand for parts grows with them. Whether Indian suppliers can capture that demand depends on cost, technology and how fast they can add capacity.
The FY28 timeline is short. Building a cell line or a solar glass plant takes years, not months. Financing, land and equipment lead times all bite.
What to watch
- How much of the $7.8 billion is expected to be sourced domestically.
- Whether cell manufacturing capacity comes up in time to feed module lines.
- Import trends for glass, frames and backsheets, which remain heavily China-dependent.
- Any change to customs duties that shifts the economics for local suppliers.
The Economic Times report was published on November 5, 2026. It did not name the firms behind the projection or break down the market by component segment.
For now, the headline number is the story. The details behind it will decide whether India's solar buildout creates a real component industry or just a bigger import bill.
Source: The Economic Times · 5 Nov 2026
Comments
Be the first to comment.
Leave a comment